Perspectives

There’s Beta in my Alpha! (Part 2)

Get Insights in Your Inbox

shutterstock 410963488

I received some feedback asking whether the high correlation of managers both to beta and to each other applies to “Aggregate” managers as well. As a brief follow-up to the previous post, I thought I would share results we obtained from the eVestment Analytics database of managers benchmarked to the Barclays Aggregate index.

The bottom-line: Aggregate managers are even more highly correlated with the credit markets and with each other than are Long Gov/Credit managers. For example, the Aggregate managers’ excess performance had a median correlation with the credit market of nearly 0.7. Alternatively, the “beta” of the managers’ excess return to the credit markets is about 0.2, an implied average overweight to credit of 20%!

We have updated the earlier graphs to reflect our new findings.
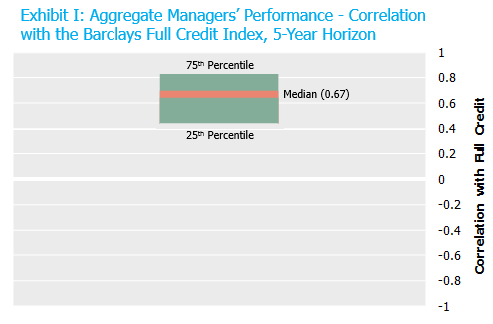
Source: Based on data from 03/31/11 through 03/31/16 from eVestment Analytics, Bloomberg, and Barclays.
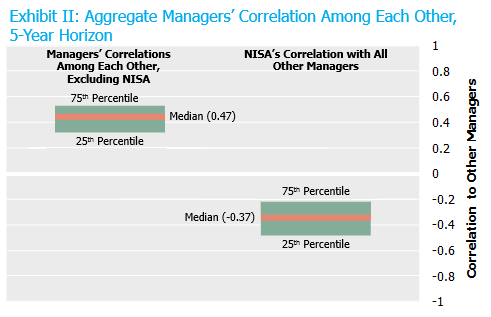
 

Source: Based on data from 03/31/11 through 03/31/16 from eVestment Analytics, Bloomberg, and Barclays.
Share

Partner With NISA

Discuss Your Portfolio Objectives with Us

Insights to Your Inbox

Receive timely updates from NISA delivered to your inbox. Select the topics most relevant to your interests.

Topics of interest(Required)
Name(Required)

We respect your inbox. Unsubscribe anytime.

Agree to Terms

Please review and accept the following to proceed.

I have read and agree to the Terms of Use, Disclaimer, PSRX Disclaimer and Privacy Policy. I am either (i) an investment professional and an employee of an institutional investor, or a consultant to an institutional investor, or (ii) an employee of, or a student in, an institution of higher learning and I am involved in the study, research or teaching of subjects related to investments, finance, or economics. I reside in the United States or Canada. I understand that the information is not and should not be regarded as investment advice or as a recommendation regarding a course of action.

By clicking “Accept” below, you hereby acknowledge, understand and accept the foregoing.