While the topic may not have come up at the Thanksgiving table, it’s one of the most discussed issues in the markets right now: why have swap spreads gone (so) negative? Ask ten people and you’ll get ten different answers—and ten different recommendations for what to do about it. Here’s the eleventh.
In a nutshell, the fixed rate on long-dated interest rate swaps fell below the yield on Treasuries of equivalent maturities during the financial crisis and, with few exceptions, has stayed negative ever since. This negative spread has become especially pronounced recently and in fact is no longer limited to the long end of the curve. On its face, the market seems to be valuing swaps as safer than U.S. Treasuries, which are usually considered the proxy for the “riskless” rate. Below are two charts that show the recent history of spreads: the first is an illustration of 30-year spreads since 2007, and the second reflects spreads over the curve from a few dates in the past.
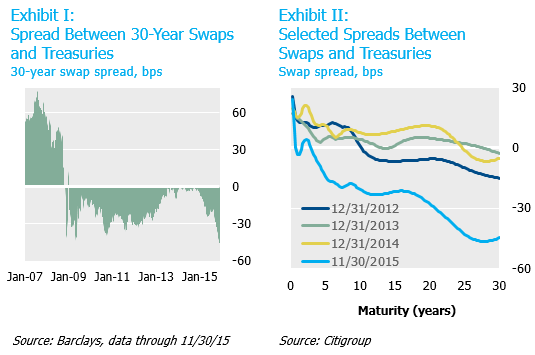
So what is driving these negative spreads?
There are a few explanations we believe are playing a role:
- A widespread desire to hold on to cash, resulting in a preference to use swaps rather than physical securities to achieve duration objectives.
- A supply/demand imbalance for swaps, with a relative scarcity of traditional pay-fixed entities (for example, mortgage-related hedgers) combined with increased demand for the receive-fixed side (perhaps driven by hedging of heavy new corporate bond issuance).
- Selling of Treasuries, particularly by foreign sovereign entities, and the termination of the Fed’s QE3 program.
- Regulatory developments, which have led some market participants (think hedge funds and broker/dealers) to alter their traditional behavior.
We maintain our view that swap spreads can remain negative, particularly at the long end of the curve. Given that swap rates don’t have an underlying physical market like Treasuries, swap spreads can dance to the beat of their own drum with no direct mechanism to bring them in line with other markets. There is no law of nature that says swap spreads have to be positive, and we see no reason negative spreads can’t persist.
Even if they continue, however, negative swap spreads may offer opportunities for defined benefit plans hedging their liabilities, or anyone investing in fixed income. Some may choose to allocate that dear cash to now cheap Treasuries. Others who use derivatives to extend duration may use Treasury-based derivatives rather than interest rate swaps, while those who use derivatives to shorten duration may use swaps rather than Treasury-based derivatives.
Our bottom-line advice is this: think about what role swaps and Treasuries play in your program before implementing a market view. A tactical reorientation within a specific hedging context, rather than a large macro bet, may be the most appropriate way to take advantage of this “anomaly.”