Markets are currently implying nearly an 80% probability that on December 16th the fed funds target range will be raised by 25 basis points. This expected increase will be the first rate hike since June 2006 – when a share of Lehman Brothers cost more than a share of Apple, and when a lot of today’s Wall Street traders were working summer jobs between semesters in college.
If the overnight rate is raised, we will finally have an answer to a question market participants have been asking for quite some time: when will the Fed get off of zero? That may be the only answer provided on December 16, however, as the Fed has a delicate task ahead.
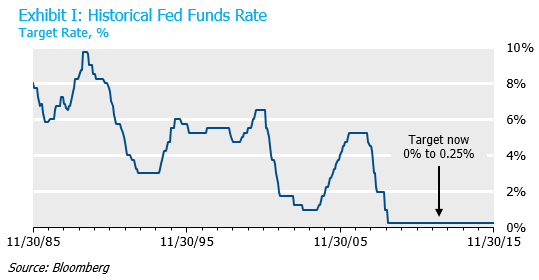
Historically, the Fed affected the overnight funds rate by managing the supply and demand of bank excess reserves, which before the 2008 financial crisis totaled in the low billions. Now that bank excess reserves are approximately $2 trillion, however, the Fed will have to employ different tools to move the overnight rate, including paying interest on excess reserves and utilizing an overnight reverse repurchase facility. Furthermore, since the financial crisis, China’s central bank, the European Central Bank, and perhaps a dozen other central banks around the world have lowered rates and then raised them, only to lower them again.
It’s easy for us to say after the fact, but most market participants (including NISA) think the fed funds rate probably should have been raised already. Either way, this first Fed rate hike may raise more questions than it will provide answers. Here are a few.
- Now that they’ve started, how quickly will they go?
- What will be the terminal fed funds rate?
- How well will the different tools work?
- Against a backdrop of global monetary accommodation, will Fed rate hikes lead to a materially stronger US dollar, retarding economic growth and keeping inflation low?
- Will higher US rates harm already fragile emerging markets – potentially leading to a tipping point for some?
- How will an increase in short rates be transmitted across the yield curve?
Of course, the Fed has said on numerous occasions that the course of monetary policy is data dependent, and so the answer to at least some of these questions very well may be, “it depends.”