Part 3: Mitigating the Cost of Private Credit’s Illiquidity
The Role of HY CDX as a Private Credit Proxy
Key Takeaways from Parts 1 and 2
In the first two installments of this series, we highlighted a few critical observations:
- Private credit offers an attractive illiquidity premium. After meticulously adjusting for duration, leverage and pricing convention differences, we find that private credit provides a meaningful excess return over comparable credit quality indices (e.g., high yield), approximately 3% over the last 20 years.
- A strikingly large proportion of this premium accrues to the manager, not the asset owner. We estimate a net-of-fee, realized illiquidity premium of only 0.6% over the last 20 years. Accordingly, 80% of this premium is lost due to management fees.
- Fund-level leverage is expensive. To increase returns, many private credit vehicles utilize fund-level leverage of approximately one turn. The borrowing cost, often SOFR + 150 to 250 bps, when combined with management fees and incentive fees, absorbs 50-80% of gross spreads before default losses.
- More efficient sources of leverage are available. Investors can increase returns by using lower-cost forms of leverage, such as HY CDX. This approach enables investors to capture the illiquidity premium of private credit without incurring unnecessary costs.
Investor Headache: Managing Private Credit Exposure
Beyond fees and expensive leverage, private credit’s illiquidity creates another significant challenge that we have not previously addressed: the difficulty of maintaining target policy allocations. The investment process for private credit—characterized by capital commitments, gradual capital calls and unpredictable distributions—makes it nearly impossible to remain consistently invested at policy weight.
In this paper, we estimate the potential performance implications of underinvestment in private credit and demonstrate that more liquid exposures, specifically HY CDX, can effectively address the challenges facing private credit investors. Once again, our conclusion is that these markets can work in harmony and complement one another, enabling investors to better achieve their objectives.
Impact of Structural Underweight to Private Credit
While many investors have sought to increase their private credit allocations in recent years, the long ramp-up period has often resulted in a systematic underweight relative to policy targets. Structural underweights can persist for years and cause significant performance drag, potentially negating the benefits of the asset class.
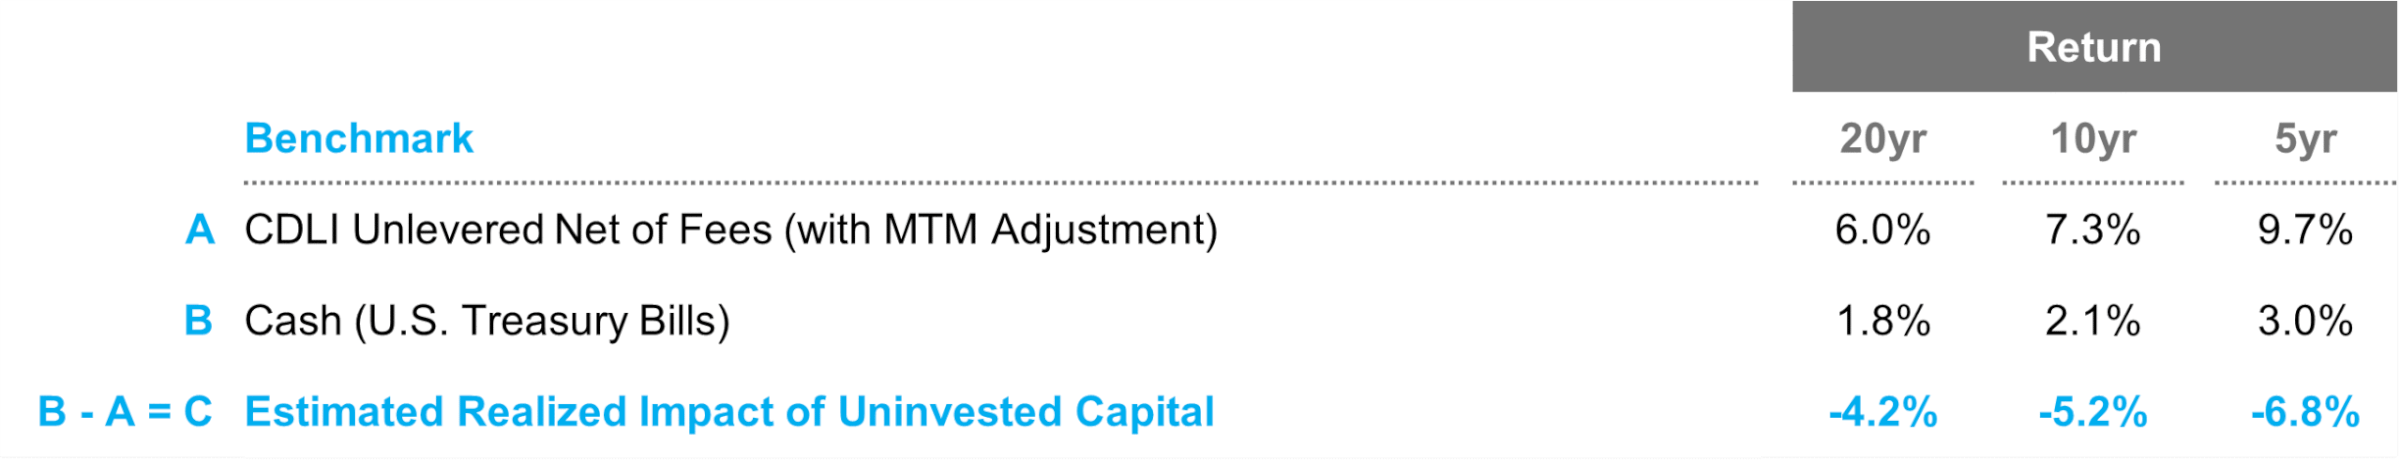
Figure 1: Estimating the Realized Impact of Uninvested Capital
Sources: Bloomberg, Cliffwater Direct Lending Index, NISA calculations. All rights reserved. Reproduced with permission. Date range: Period ending 9/30/2025.
The drag from uninvested capital has been substantial, ranging from 4.2% to 6.8% annually across different time horizons. When investors hold cash while waiting for capital calls or when distributions return capital that cannot be immediately redeployed, they face a persistent headwind to achieving policy returns, particularly during strong market environments. We should point out that some investors may choose to deploy this uninvested capital by increasing exposure to other asset classes, including public equity. This approach can alleviate the return drag, but often introduces material economic tracking error relative to policy targets.
A Liquid Solution: HY CDX
Fortunately, public markets offer a straightforward solution that can largely eliminate this performance drag while providing the liquidity necessary to precisely manage overall credit exposure. By overlaying uninvested cash with HY CDX, investors can maintain their desired credit allocation during the ramp-up period, during unexpected distribution events, and throughout the ongoing management of their private credit portfolio.
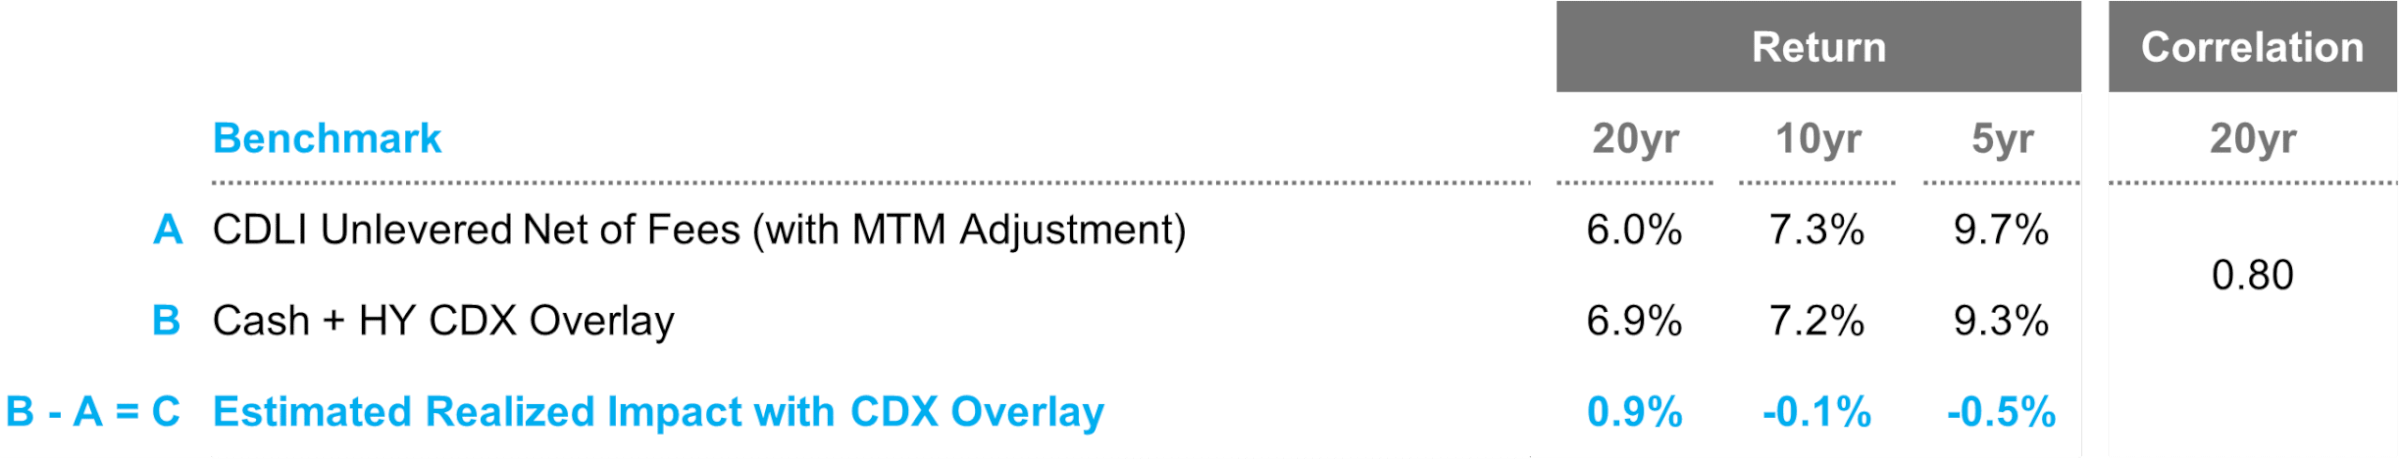
Perhaps most importantly, the historical returns demonstrate that this approach delivers performance remarkably like that of private credit. The table below compares the returns of a cash plus HY CDX overlay strategy with private credit returns, after making the appropriate structural adjustments.
Figure 2: Estimating the Realized Impact of Uninvested Capital—with a CDX Overlay
Sources: Bloomberg, Cliffwater Direct Lending Index, NISA calculations. All rights reserved. Reproduced with permission. Date range: Period ending 9/30/2025.
While public markets cannot replicate the smoothed return profile reported by private credit funds, after adjusting for observed price-to-book movements, the estimated correlation between HY CDX and private credit is significant—0.80 for quarterly returns over the prior 20 years. This demonstrates that liquid public market exposures can be a highly effective proxy for private credit exposures through time. Importantly, investors can manage their desired economic exposures precisely and stay aligned with key investment objectives.
Conclusion
Private credit can be a valuable component of institutional portfolios, offering diversification and an illiquidity premium after careful structural adjustments. However, when the goal is to add leverage to credit exposures—or to maintain policy exposure while capital is uncalled—HY CDX provides a far more efficient, liquid, and cost-controlled solution than structural fund-level leverage.
Accordingly, investors should consider a two-part approach: allocate to unlevered private direct lending where it earns its way in, and utilize liquid overlays to source incremental leverage and maintain overall credit exposure targets. In our opinion, this approach preserves the economics of private lending while addressing three key limitations—high fees, cost of leverage and illiquidity—resulting in a more efficient and more flexible solution across market regimes.