Derivative Overlay Strategies
Separate Portfolio Exposure from Capital Allocation
$
183b
Derivative Overlay Strategies Under Management
as of 6/30/2026
Our Approach
We are the largest U.S. institutional overlay asset manager[1], developing customized strategies including beta overlay, duration overlay and systematic strategies, among others. Strategic derivative implementation demands both operational expertise and the commitment of highly engaged client service and investment strategy professionals, supported by dedicated technology and talent. Our approach spans beta replication, systematic risk premia and commodity exposure—each built around the client’s specific objectives rather than a standardized product—and we support clients from initial program design through instrument selection, trade execution, collateral management, ongoing monitoring and customized reporting.
From the Expert
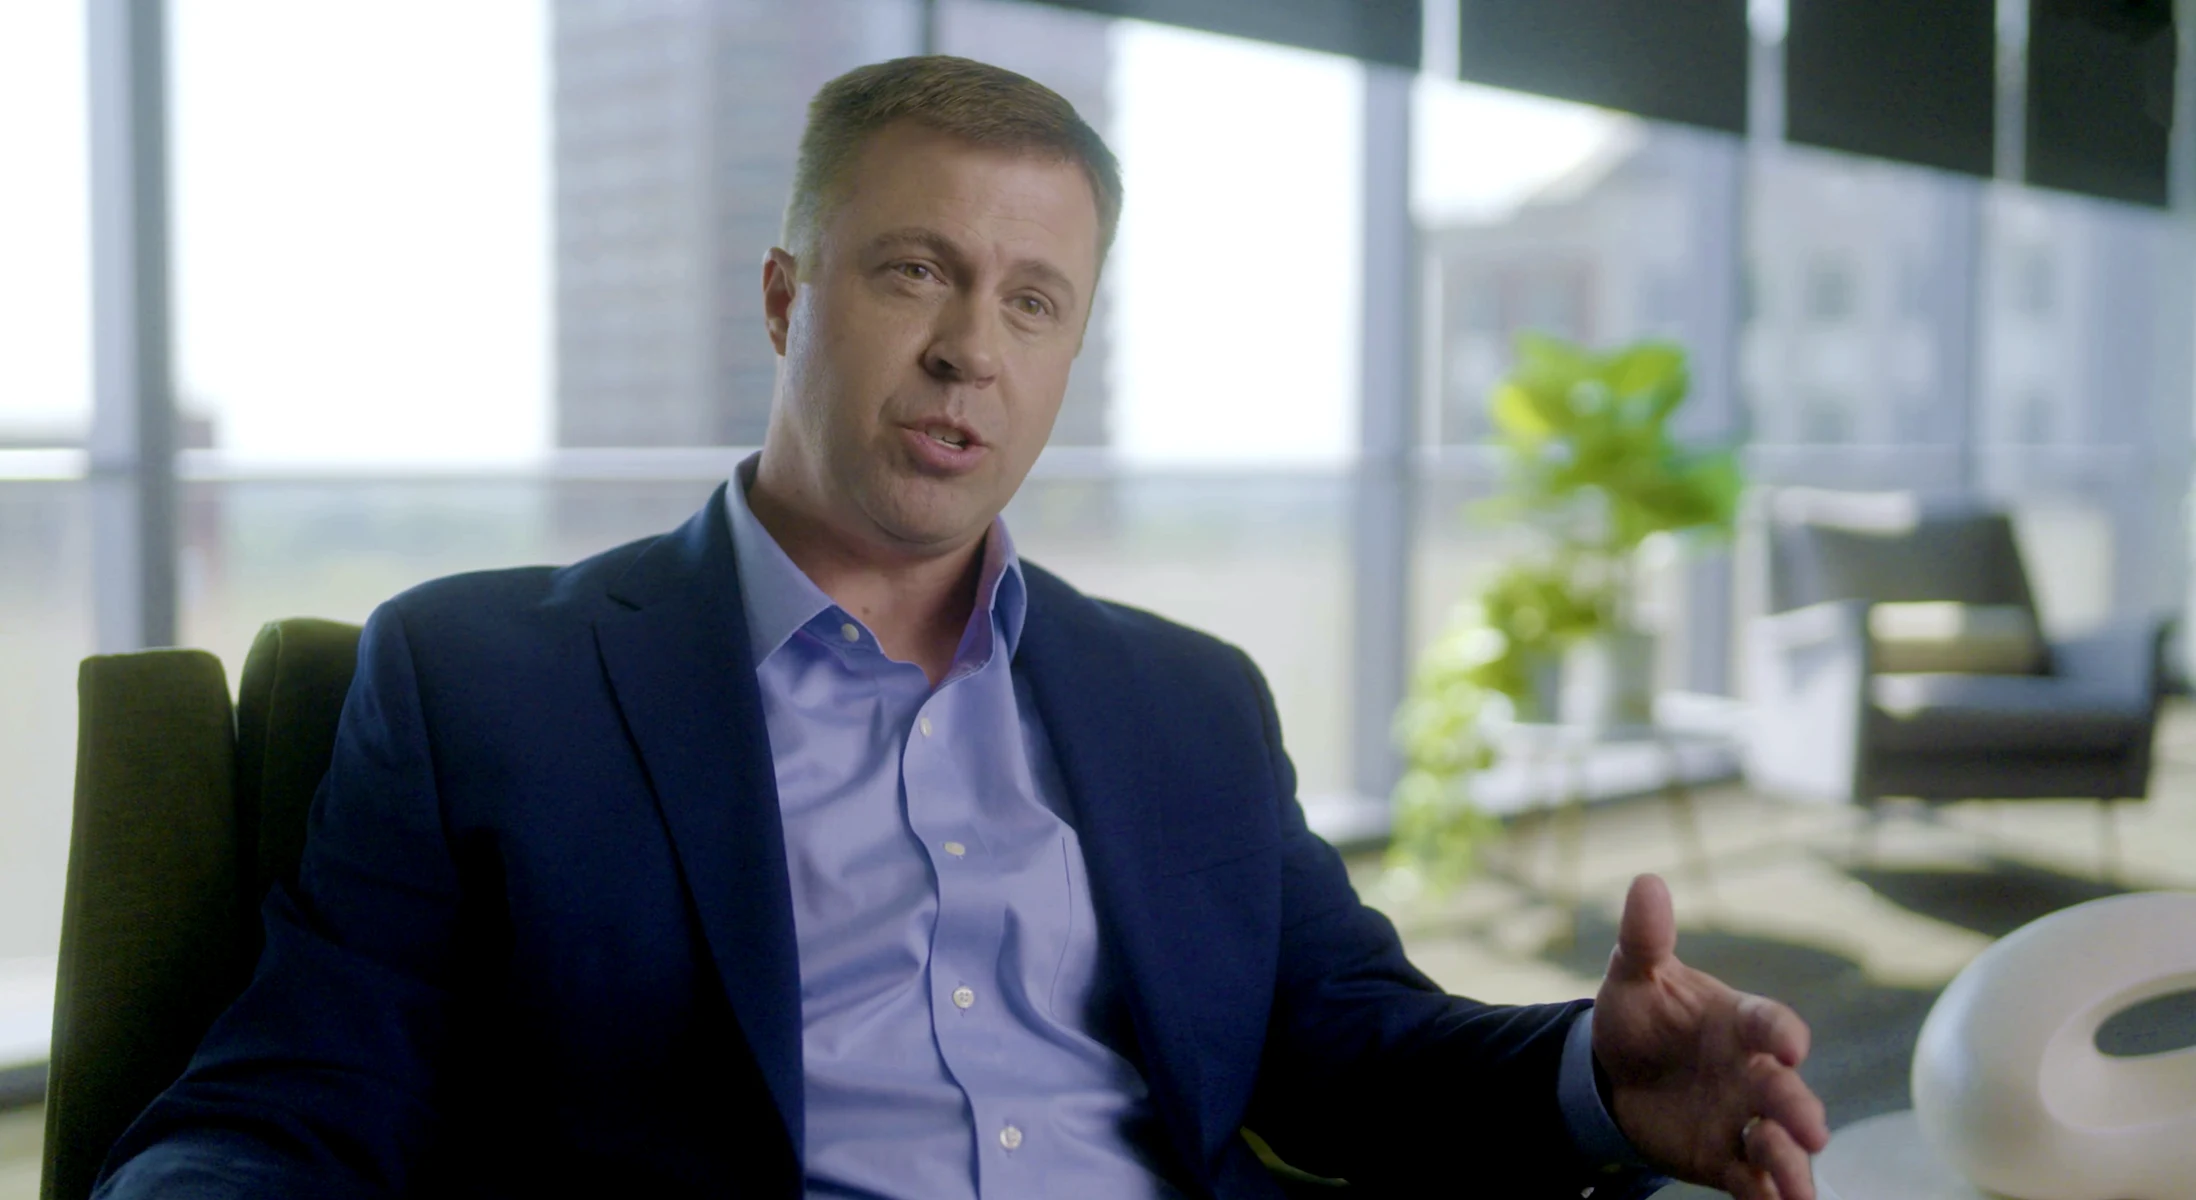
Clients look for customization, operational rigor, and collaborative thought partnership.”
Hear more about our overlay strategies.
Director, Client Services
Liability Management
Interest rate hedging strategies that seek to manage risk in pensions and other liabilities.
Learn more about Liability Management
We implement a wide range of liability hedges for objectives ranging from partial to complete hedging. No two liabilities are the same and our customized approach utilizes a breadth of instruments including swaps, futures and repos to provide quality hedges in a cost-efficient manner. Liability hedges are managed with a holistic approach and can be cognizant of existing hedge exposures elsewhere in a portfolio when determining the overlay needed to complete a hedge.
Beta Overlay
Asset class replication, cash securitization and rebalancing strategies using derivatives.
Learn more about Beta Overlay
We utilize a multi-instrument approach within our beta overlay programs to establish or maintain selected policy exposures. Our focus spans instrument selection, cost reduction, risk management and program efficacy—designed around each client’s specific objectives rather than a standardized product. Beta overlay can also serve a dynamic rebalancing function, using synthetic exposures as a tool to rebalance a plan’s overall asset allocation without requiring immediate physical trades across managers.
Systematic Strategies
We access systematic strategies across multiple asset classes—including cross-asset trend, volatility, and carry—which may appeal to investors seeking differentiated sources of return.
Learn more about Systematic Strategies
We design our own strategies, implement those designed by third parties, or work directly with investors on their own strategies. Each approach requires significant evaluation to identify the underlying drivers of return and risk.
Commodity Overlay
Thoughtful implementation of commodity exposure via various benchmarks and instruments.
Learn more about Commodity Overlay
We implement programs targeting active or passive exposure to specific commodities or broad-based commodity benchmarks. We believe our thoughtful approach to implementation across the commodity curve can improve outcomes relative to our client’s benchmark.
NISA’s Derivative Overlay Strategies
A NISA portfolio manager on managing fixed income risk across market environments.
Derivative Overlay Perspectives
Why NISA
Our Distinguished Approach
We partner with clients to build tailored solutions in pursuit of unique goals. Our style seeks consistent outcomes with high-quality, risk-adjusted returns.
Authentic Alpha
Actively managing specialized strategies across asset classes and markets, emphasizing diversification and proven processes that strive to deliver consistently high information ratios.
Beta Optimization
Capturing targeted market exposures efficiently, minimizing uncompensated risks and identifying opportunities created by structural gaps in market conditions.
Strategic Partnership
Cultivating enduring partnerships that reflect a deep understanding of client objectives with portfolios designed to deliver strategic outcomes.
Partner With NISA
Discuss Your Portfolio Objectives with Us
1 Source: Pensions & Investments (P&I). Rankings were based on U.S. institutional, tax-exempt assets managed internally (covered for overlay) as of December 31, 2025; published on June 15, 2026. NISA paid a standard fee to access the full set of data published by P&I. Other survey participants may have reported overlay strategies on a basis other than notional values and, as such, direct comparison and rankings may not be appropriate. See www.pionline.com for more details.
There is no assurance that the investment strategies will be successful. Investing involves many risks, including market-based risk, and it is possible to lose money.
Market-based risk is associated with the underlying market exposure, to include general equity, interest rate and other risks. Counterparty risk could include a counterparty default, where a loss on uncollateralized mark-to-market could be incurred by the client and new positions would need to be put in place to maintain exposure. There will likely be some amount of tracking error, or basis risk, between the derivative portfolios used to replicate exposure and the underlying benchmarks. Instrument liquidity risk could impact the ability to implement trades or could increase the transaction costs associated with trades. Operationally, strategies that involve executing trades across multiple exchanges, countries, and currencies introduce operational risks between the custodian, dealers, and asset managers.